Stuck in a Long-Term Annuity and Need Cash? Here Are Your Options
Being locked into a 10-year annuity doesn't mean you're out of options. Here's what financial experts say you can do.
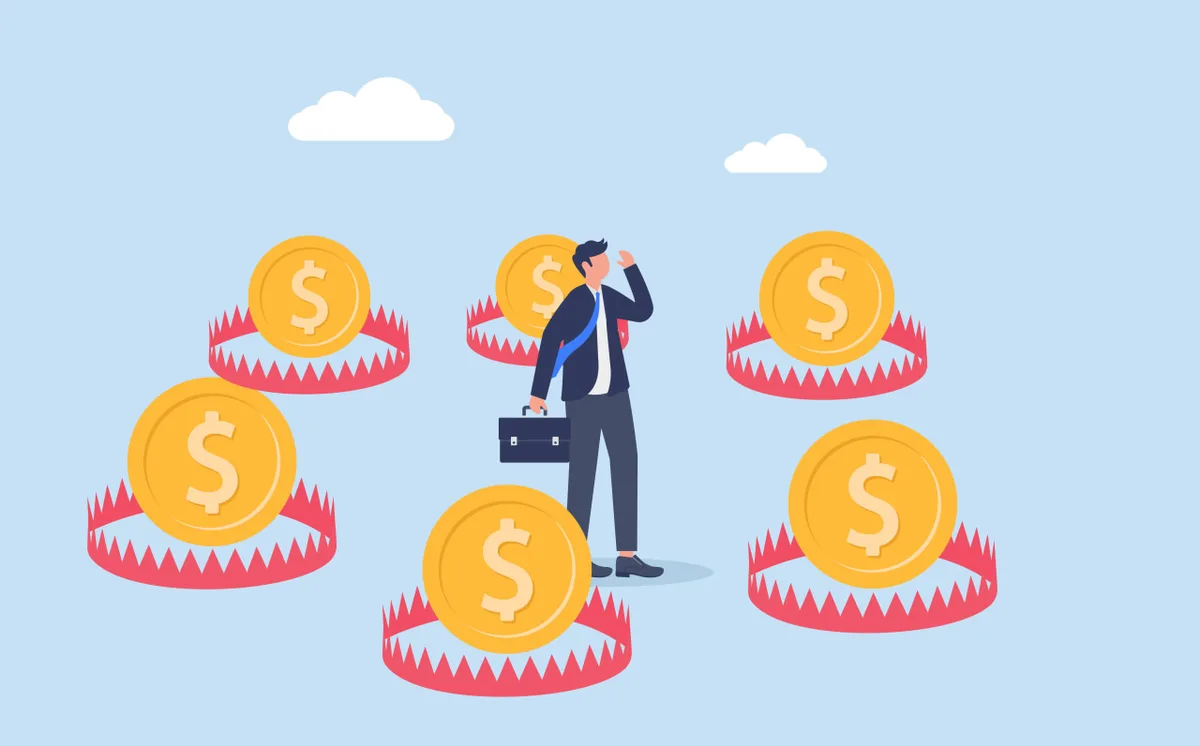
Annuities are designed for patience — structured financial products that reward those who can leave their money untouched for years, sometimes decades. But life rarely cooperates with long-term financial plans, and for someone who self-identifies as a "spender" and finds themselves strapped for cash mid-contract, the situation can feel like a trap with no exit.
The core tension here is a familiar one in personal finance: liquidity versus growth. Annuities, particularly those with multi-year guarantee periods like a 10-year contract, typically impose surrender charges for early withdrawals. These penalties can be steep in the early years of a contract and taper off gradually, meaning the timing of any exit strategy matters enormously to the net financial outcome.
Read more Why Some Experts Think Retirement as We Know It Is Ending →
There are, however, degrees of flexibility that many annuity holders don't fully realize they possess. Most contracts include a free withdrawal provision — commonly around 10% of the account value annually — that allows access to some funds without triggering surrender charges. Understanding the specific terms of the contract is the essential first step before making any move. Tax implications also enter the equation: withdrawals from a deferred annuity are typically taxed as ordinary income, and if the holder is under 59½, a 10% IRS early-withdrawal penalty may apply on top of that.
For those whose cash needs exceed what free withdrawals can cover, other avenues exist. Selling the annuity on a secondary market is one route, though buyers will discount the purchase price significantly. Annuitizing a portion of the contract — converting it into a stream of income payments — is another path some insurers permit. In genuinely dire financial circumstances, some carriers may also waive surrender charges under hardship provisions, though these are contract-specific and far from guaranteed.
The broader lesson is that annuities demand careful pre-commitment analysis, particularly for individuals who know they have a tendency toward spending or who may face unpredictable cash needs. Locking into a decade-long product without a clear liquidity plan can create real financial stress. Continue reading at MarketWatch.com